What is a holding company?

A holding company is a private limited company (BV) that owns the shares of one or more other BVs, so you keep your profits and assets separate from the risks of your day-to-day work.
The question of what a holding company is usually comes up when your business grows and you have profit left over that you don't immediately need personally. Below you can read how the structure works, which types there are, what the advantages and disadvantages are and when a holding company becomes worthwhile.
What does a holding company do?
A holding company does no operational work itself. It sells nothing, provides no services and usually has no staff. Its job is to hold assets: the shares in your operating company (werkmaatschappij), and often also accumulated profit, a business property or intellectual property.
A holding company is not a separate legal form. It is a BV with a specific role, and you will come across the same structure under names such as parent company (moedermaatschappij), holding company (houdstermaatschappij) or management BV (beheer bv). Legally, it makes no difference which term you use.
A holding company is, however, a fully fledged business with its own registration with the Chamber of Commerce (KVK), its own bookkeeping and, in practice, its own business account for a holding company, so that the holding company's money does not run through the operating company's accounts.
How does a holding structure work?
A holding structure works with at least two BVs stacked on top of each other. You are the shareholder of the holding company, and the holding company is the shareholder of the operating company. This creates a legal layer between you personally and the company where the risk lies.
That setup determines where the money ends up. Revenue comes in at the operating company, the remaining profit flows through to the holding company, and only when you want it does anything go to you personally.
The role of the operating company
The operating company is the BV where the work happens. That is where the contracts with customers are, where the staff are employed and where the invoices are sent from. As a result, almost all of the business risk sits in that BV.
If things go wrong and the operating company goes bankrupt, the bankruptcy trustee (curator) can only access the assets of that BV. The business property and the accumulated profit in the holding company stay out of reach, because the holding company is legally a separate company.
Money flows between holding company and operating company
There are usually two money flows between the holding company and the operating company. The first is the management fee: the holding company hires you out as director to the operating company and charges a monthly amount for this, set out in a management agreement.
The second is dividend, the profit after tax that the operating company distributes to the holding company. If you move money back and forth without it being one of these two, a current account between BV and holding company is created, which you need to record properly and on which you charge a commercial interest rate.
What types of holding companies are there?
There are four different types of holding companies, each with its own characteristics. Holding companies differ in what else they do besides holding shares. The legal form is always the same BV; its role within the structure determines what you call it.
1. Financial holding company
A financial holding company only manages assets. It owns the shares in the operating company, receives dividend from it and holds on to that money or invests it somewhere. Nothing else happens: no customers, no revenue, no staff.
This is the form most SME entrepreneurs choose, because it is simple to manage and the annual costs stay limited.
2. Operational holding company
An operational holding company not only holds shares but also carries out activities itself. Think of a holding company that owns the business property and rents it out to the operating company, or that handles the bookkeeping and HR for the whole group.
Because it has real activities, such a holding company also bears a small part of the business risk itself.
3. Personal holding company
A personal holding company is a holding company of which you are the sole shareholder. If you work with a business partner, each of you has your own personal holding company, and those two holding companies jointly hold the shares in the shared operating company.
That is deliberate: this way each of you decides individually when to take profit out personally, without you having to agree on it together.
4. Intermediate holding company
An intermediate holding company (tussenholding) sits between the personal holding companies and the operating company. The personal holding companies are jointly the shareholders of the intermediate holding company, and the intermediate holding company is the shareholder of the operating company.
Entrepreneurs mainly use this layer in partnerships with several partners, for example to place the business property in the intermediate holding company while the work stays in the operating company.
What are the advantages of a holding company?
The advantages of a holding company all stem from the same separation: the risk sits in one place and the value in another. That provides protection, but also tax room and more flexibility if you ever want to sell.
Spreading risk across two BVs
Spreading risk is the main reason to set up a holding company. Anything that goes wrong in the day-to-day work affects the operating company: a claim from a customer, a contract that is not fulfilled, a loan you cannot repay.
Because the valuable assets are held in the holding company, they stay out of harm's way if the operating company collapses. In a single BV without a holding company, a bankruptcy trustee could sell everything in it.
Passing on profit with the participation exemption
The participation exemption (deelnemingsvrijstelling) ensures you only pay corporate income tax (vennootschapsbelasting) on the profit once. The operating company pays that tax: in 2026 it is 19 percent on profit up to 200,000 euros and 25.8 percent on the excess.
What remains after that, the operating company may distribute tax-free to the holding company, as long as the holding company owns at least 5 percent of the shares. You only pay income tax on it when you take the money out personally.
One customary salary instead of two
With a holding structure, you only have to pay the customary salary (gebruikelijk loon) once. If you are a director-major shareholder (DGA) of two separate BVs, both BVs must pay your salary under the customary salary rule, in 2026 at least 58,000 euros per BV.
If you are employed by the holding company and it hires you out to the operating company, the rule only applies to the holding company. That saves a second payroll administration and paying payroll tax a second time.
Selling your business in parts
Selling your business is easier with a holding structure, because you can transfer parts separately. You sell the shares of the operating company and keep the business property in the holding company, which you can then rent out to the buyer.
If everything is in one BV, a share transfer automatically means you also sell everything that is in that BV at that moment.
What are the disadvantages of a holding company?
A holding structure costs more money and more time than a single BV. There are three disadvantages you should weigh up in advance.
Higher costs: you set up two BVs instead of one, with the associated civil-law notary and registration costs, and every year you pay for two sets of annual accounts.
More bookkeeping: two BVs means two sets of books, two corporate income tax returns and precisely recording all transactions between them.
No absolute protection: if you have not followed the rules or have taken unnecessarily large risks, a court may rule that there was mismanagement (onbehoorlijk bestuur) and you can still be held personally liable.
That liability applies to every BV in the structure, including the holding company. The separation protects you against business risk, not against careless management.
When is a holding company worth considering?
A holding company becomes worth considering as soon as the value you are protecting outweighs the extra costs. That moment differs per entrepreneur, but there are a few situations in which it almost always comes up.
The first is structurally having profit left over that you don't need personally. As long as you spend everything that comes in, there is little to protect and you mainly pay for a second set of annual accounts.
It also comes into play with multiple business activities, a partnership with a business partner, plans to invest in property and a future sale. Have an accountant or tax adviser calculate what it would deliver in your situation, because the tax side depends heavily on your profit and your personal situation.
What does a holding company mean for your bookkeeping?
A holding company doubles your bookkeeping, and that is the part entrepreneurs most often underestimate. From the moment there are two BVs, the Dutch Tax Administration (Belastingdienst) treats them as two separate taxpayers, and you have to do the same.
In practice, there are four things you keep track of separately.
Two registrations: the holding company and the operating company are each registered independently in the Business Register of the Chamber of Commerce (KVK).
Two sets of annual accounts: each BV prepares and files its own annual accounts.
Two tax returns: both BVs file a corporate income tax return, unless you form a fiscal unity (fiscale eenheid), which is possible from a 95 percent shareholding.
Two accounts: the management fee and the dividend must visibly flow from one BV to the other, and that only works if both BVs have their own payment account.
Also pay attention to the VAT position. A holding company that only holds shares and does nothing else is often not an entrepreneur for VAT purposes and then does not receive a VAT number, which means you cannot reclaim the VAT on the holding company's costs.
Managing your holding company and operating company with GoDutch
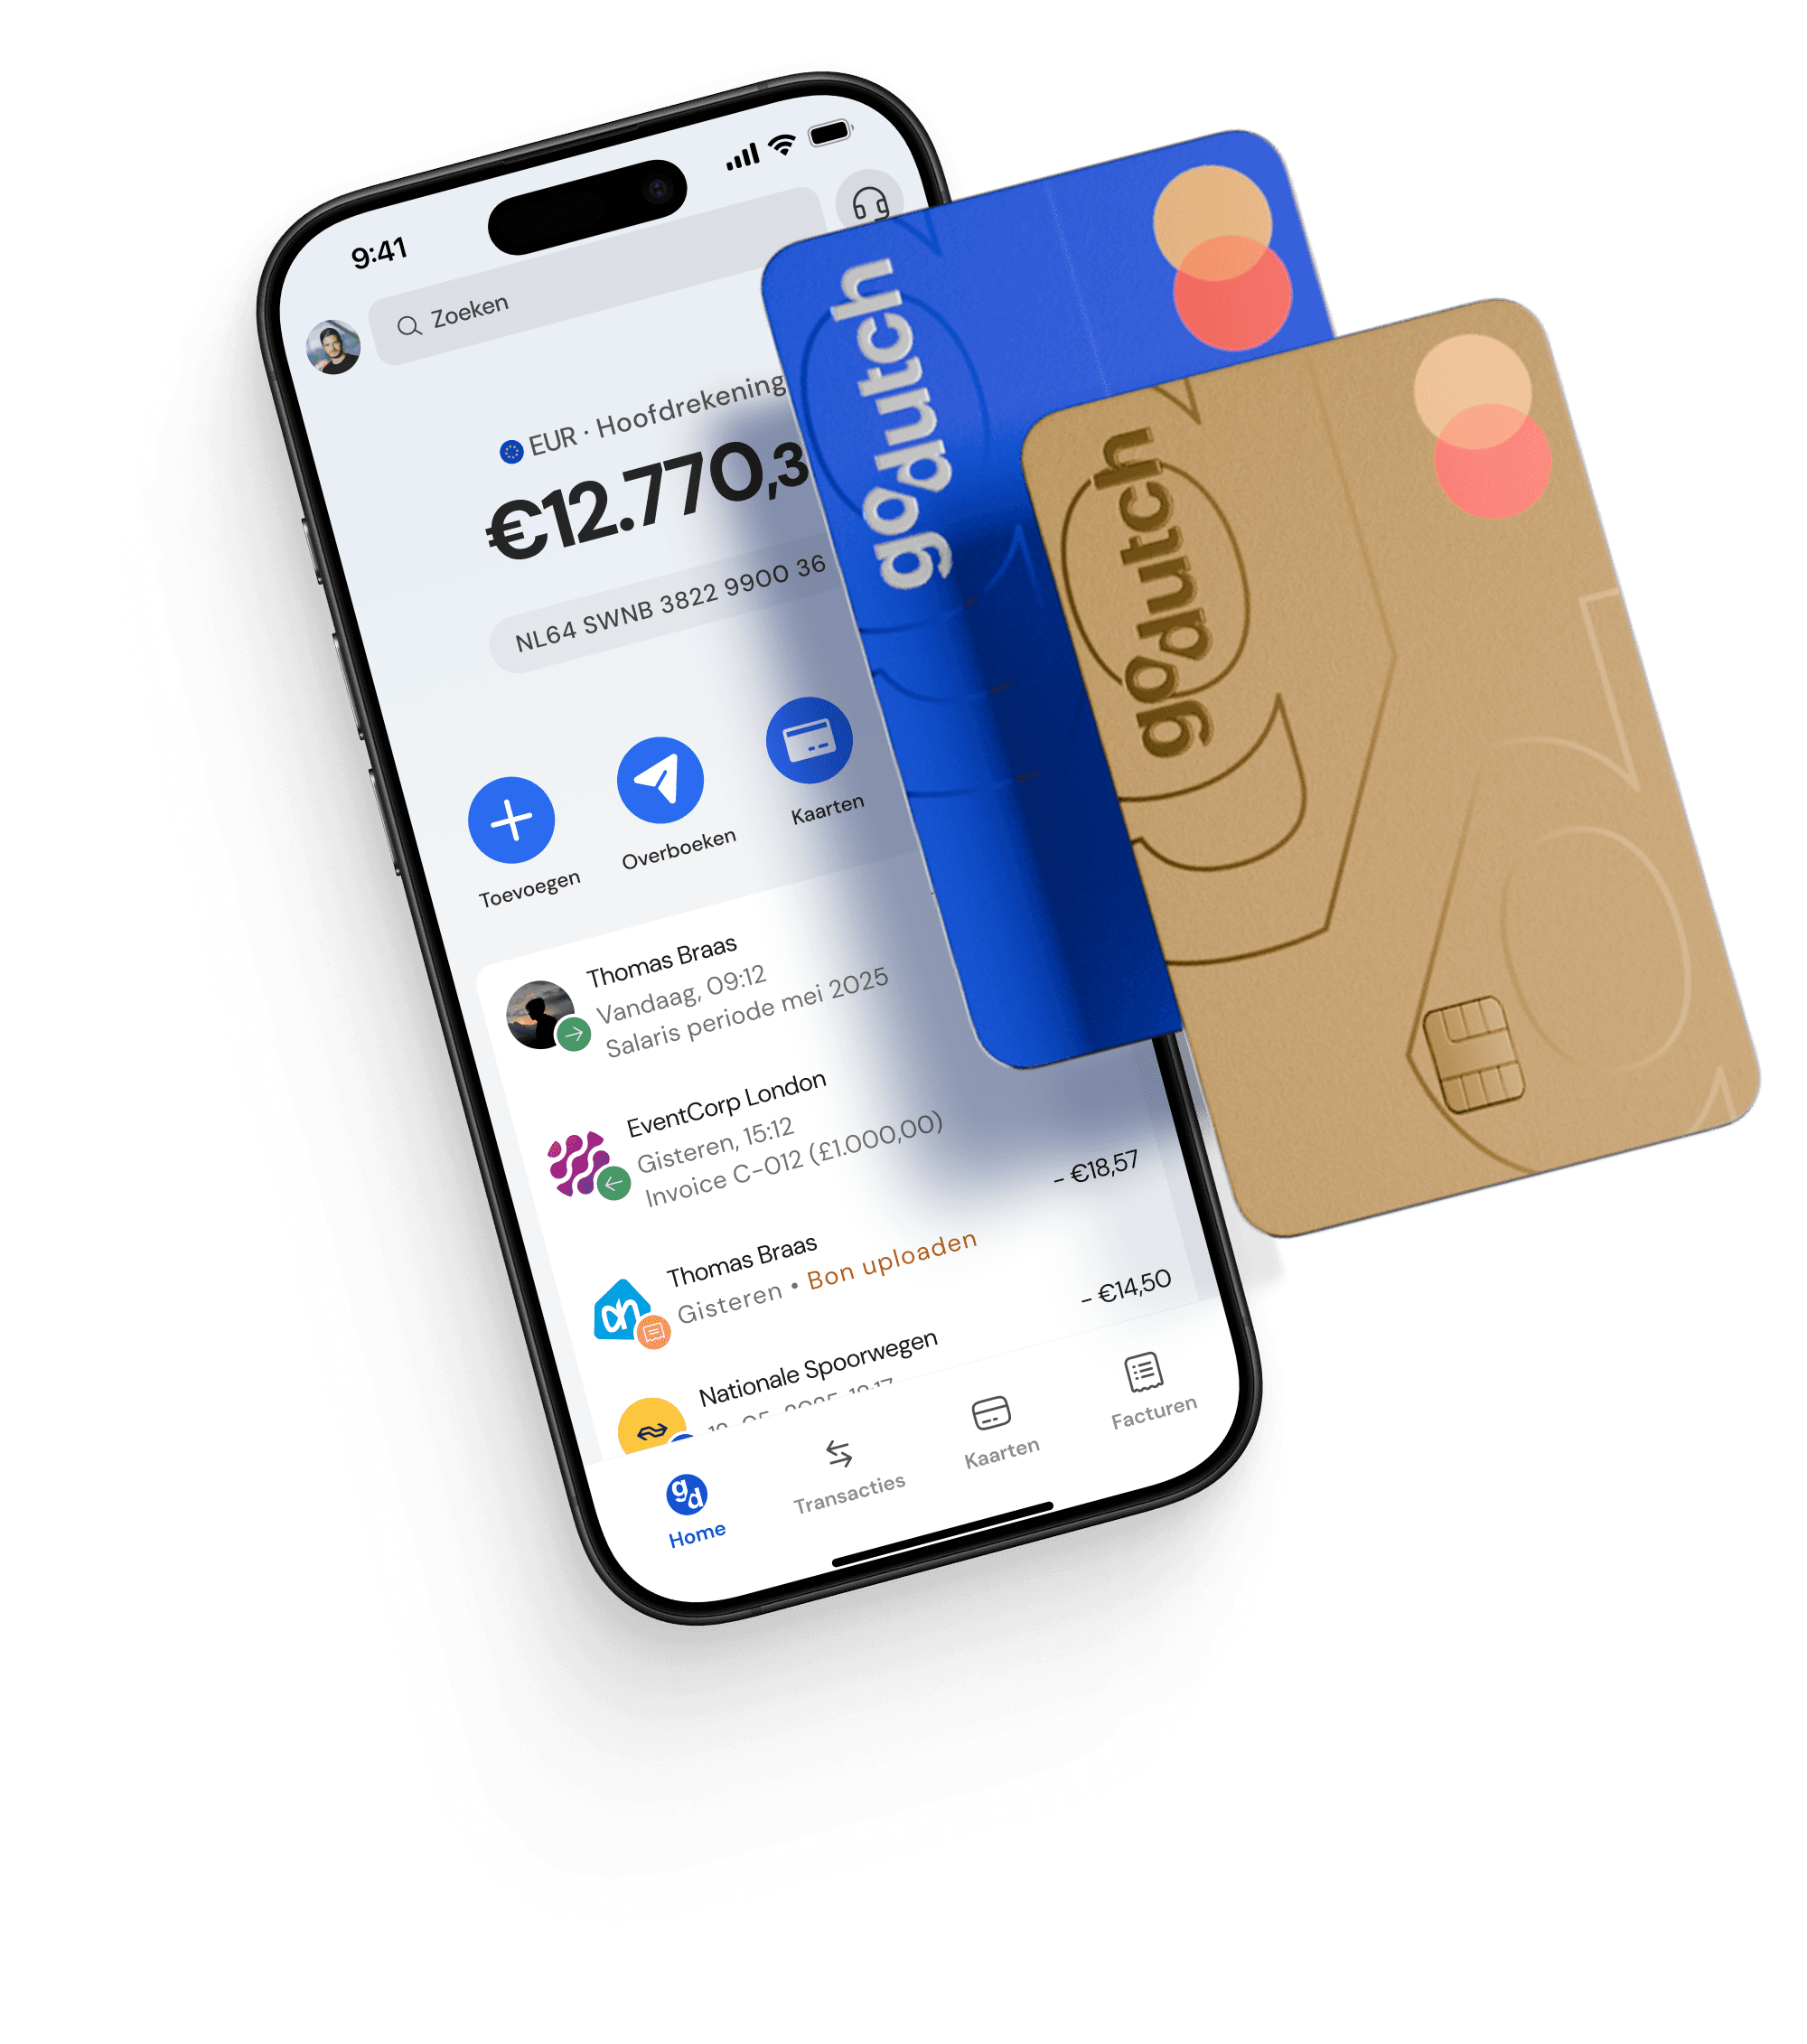
Two BVs means managing your finances twice, and that is exactly what GoDutch is set up for. GoDutch is not a bank but an all-in-one business account for entrepreneurs, with which you open a separate account for both your holding company and your operating company and switch between them in the same app.
This makes the separation you create for tax and legal purposes visible in your bookkeeping too. The management fee and the dividend payment run as ordinary transactions between the two accounts, you connect your bookkeeping to both, and you see in one overview where your money is.
How to get started with GoDutch
Are you considering a holding structure or do you already have one? Then you can open your business account with GoDutch in a few minutes. You apply for the account in 3 minutes and have your IBAN and card within 1 day, so your BV can make and receive payments straight away. If you run into anything, someone is ready to help you 24/7.
FAQ
Frequently asked questions about holding companies
How much tax do you pay in a holding company?
In the holding company itself, you usually pay no tax on the profit coming in from your operating company, thanks to the participation exemption (deelnemingsvrijstelling). The corporate income tax has already been paid by the operating company: 19 percent on profit up to 200,000 euros and 25.8 percent above that. Only when you take money out personally do you pay box 2 tax.
Is a holding company always a BV?
In the Netherlands, a holding company is almost always a BV, but that is not a legal requirement. A public limited company (nv) can also act as a holding company. The BV is the standard choice because you can set one up with 0.01 euro in starting capital and the shares are registered, which suits a closed structure.
What is the difference between a holding company and a management BV?
There is no legal difference between a holding company and a management BV (beheer bv): they are two names for the same structure. In practice, management BV puts slightly more emphasis on managing assets and holding company on holding shares. You can read more about the difference between a holding company and a BV in our separate article.
Can you set up a holding company if you already have a BV?
You can always set up a holding company later above an existing BV. You first set up the holding company at the civil-law notary and then transfer the shares of your existing BV to that holding company. How this works step by step and what to watch out for tax-wise is explained in our article on setting up a holding company.
How many operating companies can a holding company have?
A holding company can have an unlimited number of operating companies under it. Entrepreneurs with multiple activities often place them in separate BVs under the same holding company, so that a problem in one activity does not affect the other. Each operating company does remain an independent BV with its own bookkeeping and annual accounts.
Does a holding company need its own account?
A holding company needs its own business account, because it is an independent legal entity with its own bookkeeping. The management fee and dividend payments between the BVs must visibly run through separate accounts. If everything gets mixed up, the separation you create with the structure becomes unclear in the books.