What is an entrepreneur?

An entrepreneur (ondernemer) is someone who supplies products or services to others for their own account and at their own risk, with the aim of making a profit. That sounds clear-cut, but in the Netherlands the Chamber of Commerce (KVK) and the Dutch Tax Administration (Belastingdienst) each assess it under their own rules.
Below you can read what an entrepreneur is, when you count as one according to which authority, and what that means for your bookkeeping.
What is the difference between an entrepreneur and a business?
The difference between an entrepreneur and a business is the difference between the person and the structure. The entrepreneur makes the decisions and bears the risk; the business (onderneming) is the organisation in which that happens.
A business is a lasting organisation of labour and capital that takes part in economic activity with the aim of making a profit. That organisation is given a legal form, for example a sole proprietorship (eenmanszaak), a general partnership (vof) or a private limited company (BV), and is registered in the KVK Business Register (Handelsregister).
One entrepreneur can have several businesses. The Dutch Tax Administration assesses per activity whether there is a business, and only if there is sufficient connection do several activities count as one source of income.
What does an entrepreneur do?
An entrepreneur independently supplies products or services, finds their own customers and bears the consequences themselves if things go wrong. That last point is where entrepreneurship differs from employment.
In practice, these tasks come back for almost every entrepreneur:
Setting prices: you set your own rate and negotiate with your customers.
Finding customers: you bring in your own work and make your business visible.
Investing: you put money and time into materials, tools, insurance and promotion.
Bearing risk: you earn less if a customer drops out or does not pay, and you are liable for your business's debts.
Keeping your records: you keep your invoices and receipts and file your own tax returns.
That combination of freedom and responsibility is exactly what KVK and the Dutch Tax Administration look at when they assess whether you are an entrepreneur.
When are you an entrepreneur?
Whether you are an entrepreneur depends on who is answering the question. Three assessments are separate from each other: KVK decides whether you belong in the Business Register, the Dutch Tax Administration decides whether you are an entrepreneur for VAT, and the Dutch Tax Administration also decides separately whether you are an entrepreneur for income tax.
So you can be on one list and not on another. That is not a flaw in the system, but the result of three different purposes: registration, turnover tax and tax on profit.
1. When are you an entrepreneur according to KVK?
According to KVK, you are an entrepreneur if you meet three entrepreneur criteria:
Supplying independently: you supply products or services yourself, or you can show that you are preparing to do so.
Earning money: you charge more for it than it cost you to make.
Taking part in economic activity: you do business with people other than just friends and family.
If you meet these criteria, you register with KVK. If you are in doubt, KVK also looks at your investment of money and time, how regularly you work, the number of customers or clients, and your freedom to decide when, where and how you work.
After you register, KVK passes your details on to the Dutch Tax Administration. So you do not need to register separately.
2. When are you an entrepreneur for VAT?
You are an entrepreneur for VAT when you independently earn income from work with some regularity. The amount of your profit plays no role here, and even a hobby-like start can make you a VAT entrepreneur as soon as you supply on a structural basis in return for payment.
If you are an entrepreneur for VAT, you receive a VAT identification number, charge VAT and file VAT returns. If your turnover stays below €20,000 per year, you can join the small business scheme (KOR) and those obligations no longer apply.
Being a VAT entrepreneur says nothing about your position for income tax. That is a separate assessment with different criteria.
3. When are you an entrepreneur for income tax?
You are an entrepreneur for income tax when the Dutch Tax Administration classifies your income as profit from a business. That assessment goes further than your registration and looks at how you actually work.
The Dutch Tax Administration looks at these points, among others:
Profit and expected profit: do you make a profit, and is it plausible that you will keep making one? With structural losses or a very small profit, there is usually no business.
Independence: do you decide yourself how you organise and carry out your work, or do others do that for you?
Capital: do you have enough money to start your business and keep it running for a while?
Entrepreneurial risk: do you run the risk that customers do not pay or that your investment is lost?
Liability: are you liable for your business's debts?
Size and clients: do you work for several clients, and how large is your annual turnover?
If you are unsure about your own situation, fill in the Dutch Tax Administration's OndernemersCheck (entrepreneur check). It does not give a binding judgement, but it does show where you stand strong or weak.
What if the Dutch Tax Administration does not consider you an entrepreneur?
If the Dutch Tax Administration does not consider you an entrepreneur for income tax, your income falls under income from other activities (resultaat uit overige werkzaamheden). You are then a resultaatgenieter rather than an entrepreneur, but you still file a tax return.
Your profit is calculated in the same way as for an entrepreneur, so you can deduct your business expenses. What you miss out on are the entrepreneur schemes: the self-employed deduction (zelfstandigenaftrek), the starter's deduction (startersaftrek), the investment deduction (investeringsaftrek) and the SME profit exemption (mkb-winstvrijstelling) remain out of reach.
This situation is common among people who take on a few assignments a year on the side. Even then, you can still be an entrepreneur for VAT.
What types of entrepreneurs are there?
The types of entrepreneurs you come across in practice differ mainly in scale and stage. The legal criteria stay the same; what changes is the size of the business and the stage you are at.
What is a self-employed entrepreneur?
A self-employed entrepreneur (zelfstandig ondernemer) works for their own account and at their own risk and has no staff. You set your own rate, choose your customers and arrange your own insurance and pension.
Freelancer (zzp'er) is not a legal term and not a legal form. Most self-employed entrepreneurs have a sole proprietorship, but a general partnership or a BV can also fit. So the term describes how you work, not how you are registered.
What is an SME entrepreneur?
An SME entrepreneur (mkb-ondernemer) runs a small or medium-sized business, in the Netherlands usually defined as fewer than 250 employees. Unlike the self-employed entrepreneur, this entrepreneur has staff, and with that payroll, contracts and sick leave.
The entrepreneur criteria of KVK and the Dutch Tax Administration do not change as a result. What does change is the administration: more users on the account, more payment moments and more need for control over spending per team or project.
What is a starting entrepreneur?
A starting entrepreneur is someone who has just registered and is building up their business. For tax purposes this is not a separate category, but extra schemes do apply in the first years.
The best known is the starter's deduction (startersaftrek), which you can apply a maximum of three times in the first five years of your business on top of the self-employed deduction. The condition is that you meet the hours criterion (urencriterium).
What misconceptions exist about entrepreneurship?
The most persistent misconceptions about entrepreneurship are about hours, losses and registration. They cost starters money, because they lead to deductions that go unclaimed or to tax returns that are incorrect.
Watch out for these three:
The hours criterion determines whether you are an entrepreneur: incorrect. The 1,225 hours determine whether you are entitled to deductions such as the self-employed deduction, not whether the Dutch Tax Administration sees you as an entrepreneur.
A loss means you are not an entrepreneur: incorrect. Many starters make a loss in the first years; the Dutch Tax Administration also weighs your investments, your continuity and the expectation that you will make a profit.
Registering with KVK makes you an entrepreneur for income tax: incorrect. KVK and the Dutch Tax Administration use different criteria, and the Dutch Tax Administration assesses your situation independently.
A related risk mainly arises when working for a single client. The more your work resembles employment, the greater the chance that the Dutch Tax Administration will classify it as false self-employment (schijnzelfstandigheid), with consequences for you and your client.
How can GoDutch help you as an entrepreneur?
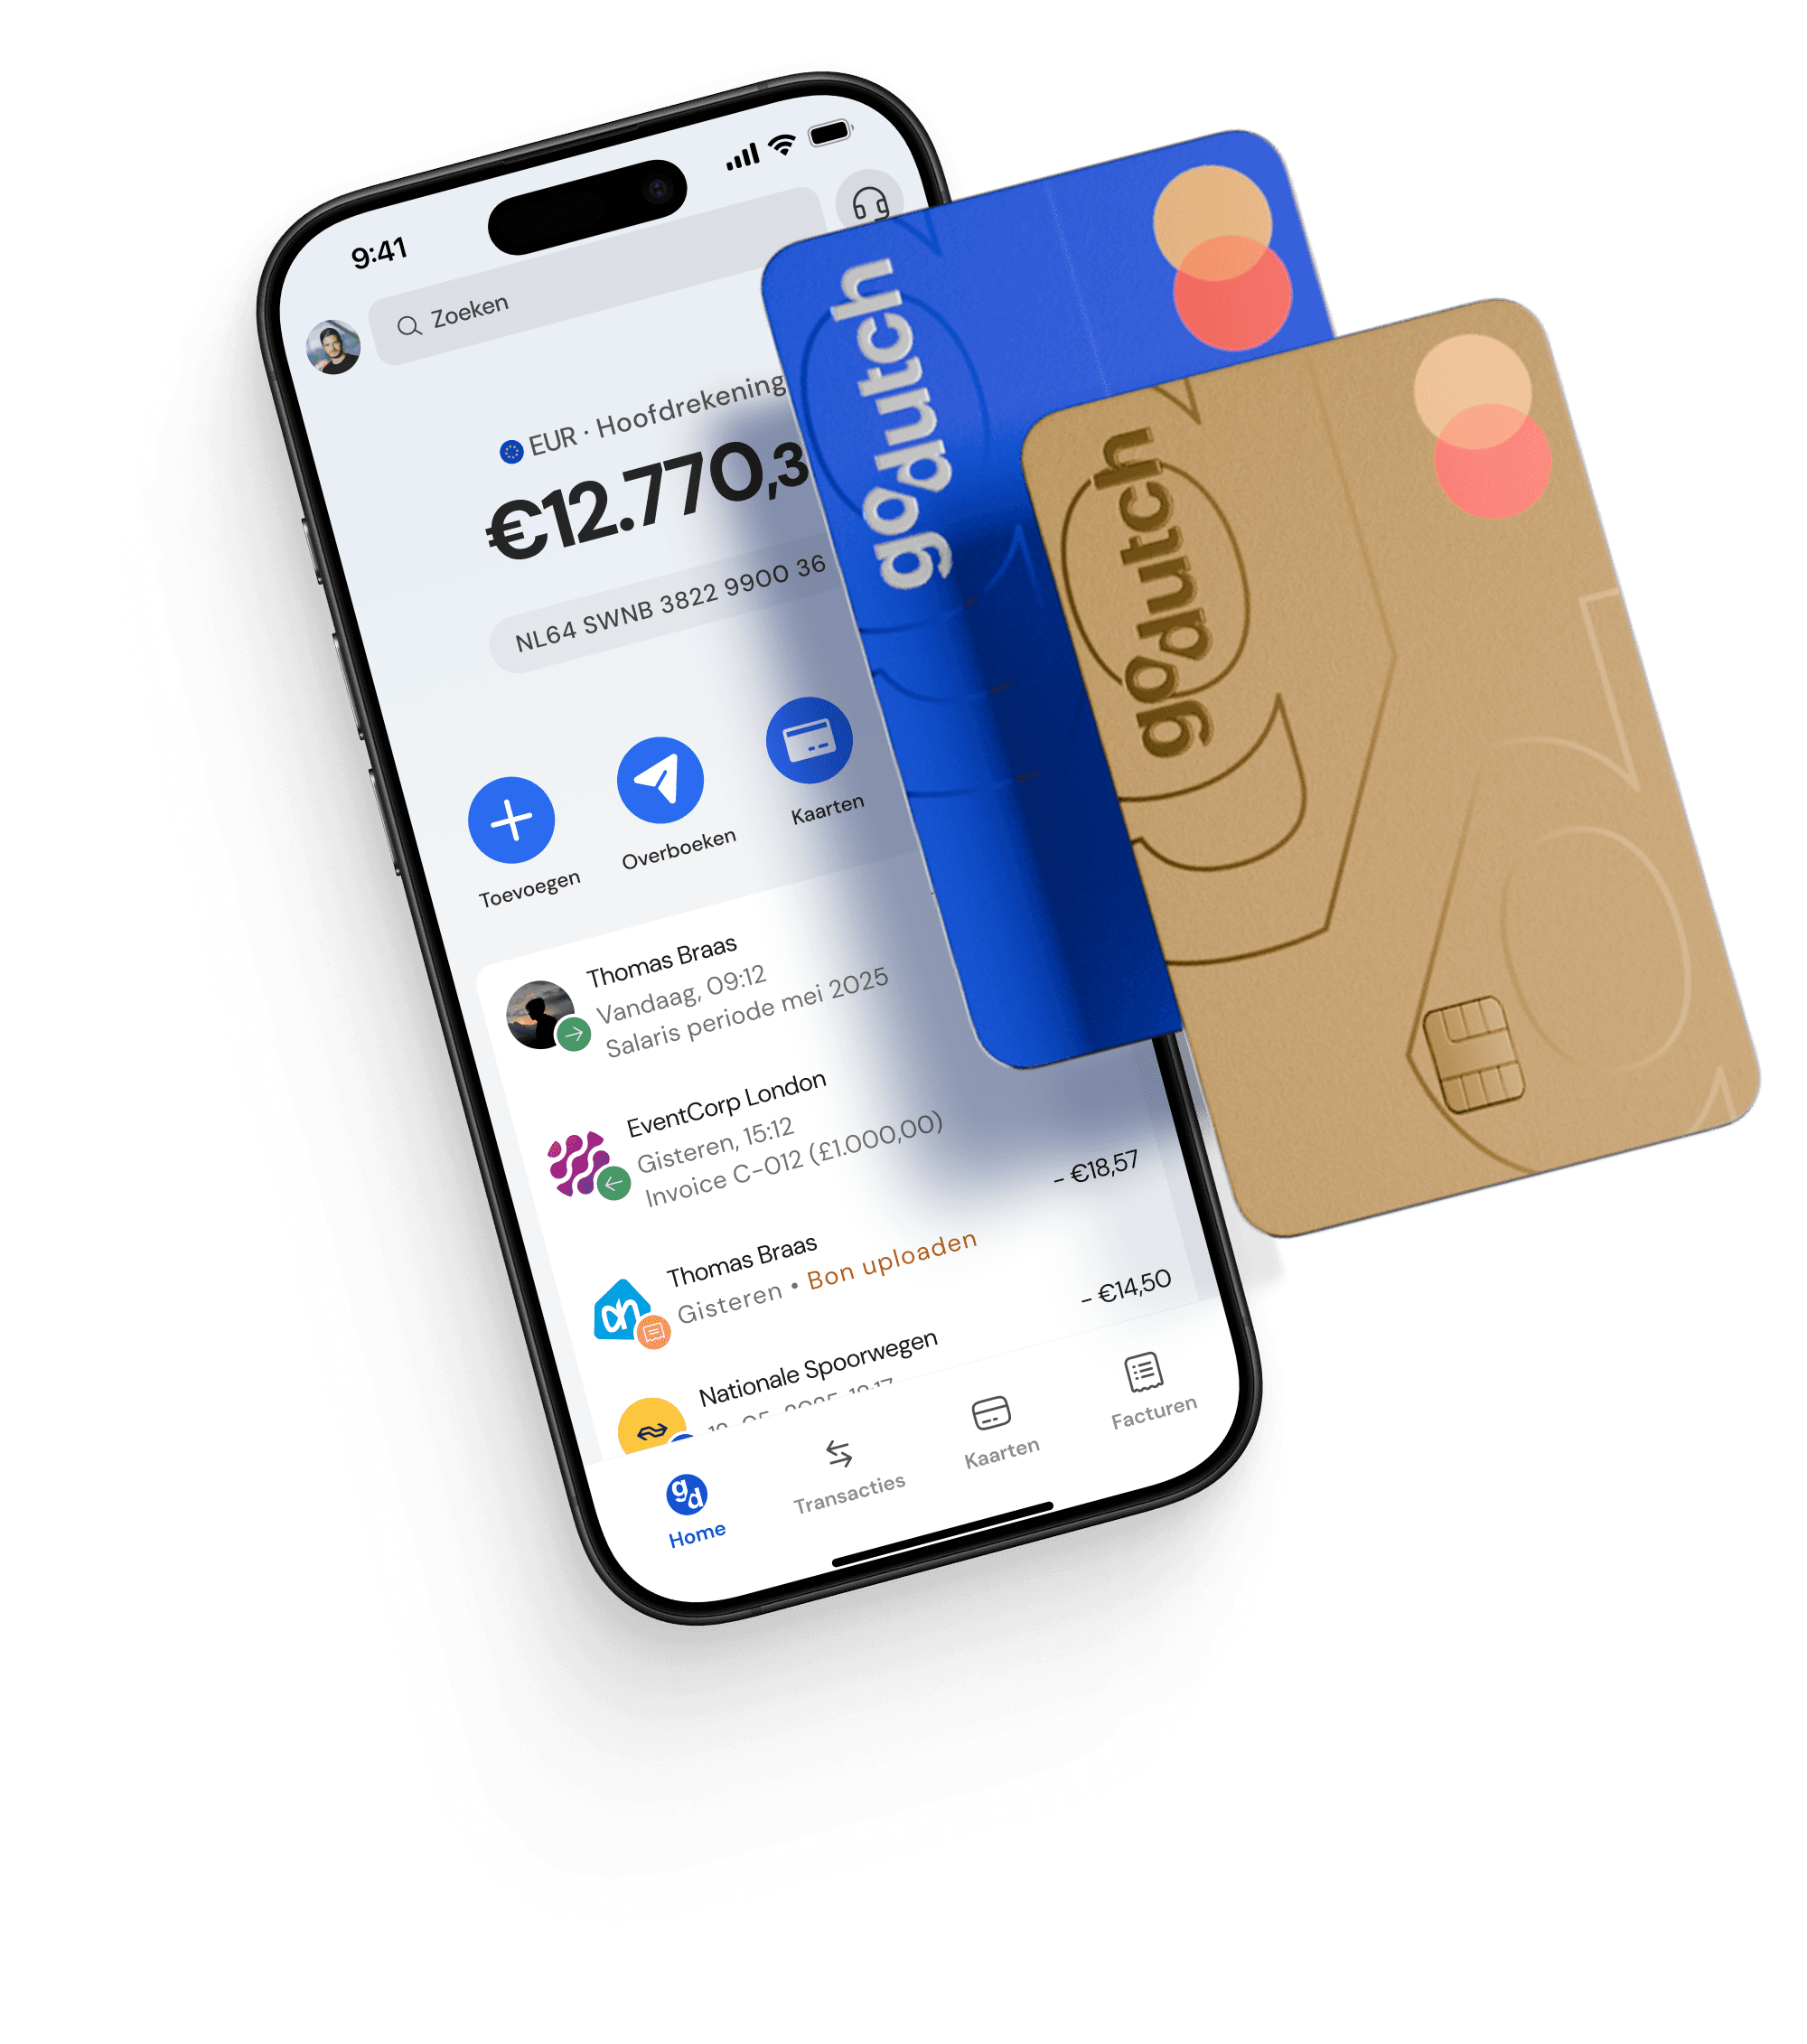
GoDutch can help you as an entrepreneur by bringing your business finances together in one place, so your bookkeeping keeps pace with your work instead of lagging behind it. We are not a bank, but an all-in-one business account for Dutch entrepreneurs.
The first thing you want to sort out as an entrepreneur is the separation between personal and business. With your own business account, you see at a glance what your turnover is and what your costs are, and that saves work with every VAT return.
You apply for your account in 3 minutes and have your IBAN and card within 1 day. The entry plan is free and has no fixed monthly fees, you connect your bookkeeping to Exact, Snelstart, Twinfield, Yuki and Jortt, among others, and you scan your receipts in seconds with the app.
You are also welcome if you do not have a sole proprietorship: a BV, a sole proprietorship, a general partnership and a foundation with ANBI status can open an account on any plan, and for an NV, an owners' association (vve), an association, a cooperative and other foundations, this applies from the Starter plan.
Have you just started and want to set up your finances properly straight away? Take a look at the GoDutch business account and open it in a few minutes.
FAQ
Frequently asked questions about being an entrepreneur
Is a freelancer (zzp'er) an entrepreneur?
A freelancer (zzp'er) is an entrepreneur as soon as they meet the criteria of the authority making the assessment. For KVK, that means independently supplying to third parties in return for payment. For income tax, the Dutch Tax Administration also looks at expected profit, independence and entrepreneurial risk, and that outcome can be different.
What is the difference between an entrepreneur and a freelancer?
The difference between an entrepreneur and a freelancer lies in the wording, not in the law. Freelancer is an informal term for someone who works on an assignment basis, usually without staff. Legally and for tax purposes, such a person is assessed against exactly the same entrepreneur criteria as any other entrepreneur.
What does entrepreneur mean in Dutch?
In Dutch, entrepreneur simply means ondernemer. The word comes from French and is mainly used in Dutch in an international or innovative context, for example with startups. In substance it refers to the same person: someone who builds a business for their own account and at their own risk.
Can you be an entrepreneur alongside a salaried job?
You can be an entrepreneur alongside a salaried job. You register with KVK, declare your salary as income from employment and your profit separately in your tax return. Whether you are entitled to the entrepreneur's deduction (ondernemersaftrek) depends on the hours criterion, which is harder to meet alongside a job.
Do you have to register with KVK as an entrepreneur?
As an entrepreneur, you must register in the KVK Business Register as soon as you meet the three entrepreneur criteria. If you do not register while you are in fact running a business, the Dutch Tax Administration can still determine that you are an entrepreneur, resulting in additional VAT assessments.
Are you an entrepreneur if you have a BV?
With a BV, you are not an entrepreneur for income tax. The BV pays corporate income tax on its profit and you, as director-major shareholder (dga), are employed by your own BV. You receive a salary and are therefore not entitled to the self-employed deduction or the SME profit exemption.